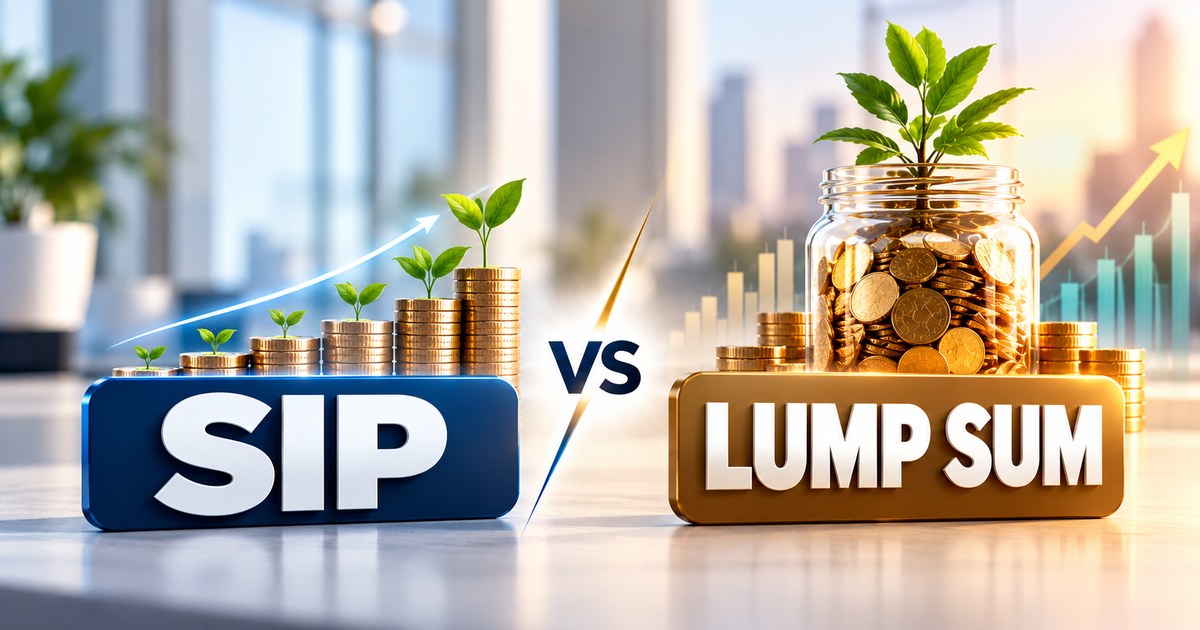
This question comes up all the time - when someone gets a bonus, a maturity payout from another investment, or simply wants to know the "right" way to invest. Should you put the whole amount in at once, or spread it out over time? The honest answer is: it depends on where the money is coming from, and what you're using it for.
Here's what SIP and lump sum actually do, in plain language.
What a SIP Actually Does
A Systematic Investment Plan (SIP) invests a fixed amount at regular intervals - usually monthly - instead of all at once. Because you're buying at different prices over time, some months you buy at a higher price and some at a lower price. This averages out your entry point over time, rather than depending on the price on any single day.
The bigger benefit for most people isn't really about pricing - it's about discipline. A SIP fits naturally with a monthly salary, and it removes the need to guess whether "now" is a good time to invest.
What Investing a Lump Sum Actually Does
Investing a lump sum means putting the full amount in on a single day - no averaging, no spreading it out. If markets rise after that day, the full amount benefits from the rise. If markets fall, the full amount feels that fall too. There's no in-between.
This isn't good or bad by default - it simply means the outcome depends more on the specific day you invested, compared to a SIP where the outcome depends on many different days over time.
When a SIP Tends to Make Sense
A SIP usually fits best when your money comes in regularly, such as a monthly salary, and when you're investing toward a goal that's still years away, such as retirement or a child's education. It also tends to suit people who are newer to investing and want to build the habit gradually, rather than deciding to invest a large amount all at once.
When Investing a Lump Sum Tends to Make Sense
A lump sum tends to fit better when the money itself arrives all at once - a bonus, an inheritance, the maturity of a fixed deposit or another investment. In these cases, spreading a one-time amount over many months just to "act like a SIP" isn't always necessary; it depends on your comfort with the amount going in on a single day, and your own goals for that specific money.
A Middle Path: Moving a Lump Sum In Gradually
For people who have a lump sum but aren't comfortable investing all of it on one day, there's a middle option - moving the money into your investments gradually over a few months, rather than either all at once or waiting indefinitely for the "right" day. This is sometimes done through a Systematic Transfer Plan (STP), where a lump sum sits in one place and is moved across in fixed instalments.
This doesn't guarantee a better outcome than investing all at once - no approach can promise that - but it can make a large, one-time decision feel less all-or-nothing for people who find that helpful.
There's no single correct answer between SIP and lump sum. The better question is usually: where is this money coming from, and how do I feel about the amount going in at once versus spread out? Once that's clear, the right approach for your situation usually becomes clear too.
Frequently Asked Questions
Can I do both SIP and lump sum at the same time?
Yes. Many people run a regular SIP from their monthly income while also investing a lump sum separately when they receive one - a bonus or a maturity payout, for example. The two aren't mutually exclusive.
Does SIP guarantee better returns than a lump sum?
No. Neither approach guarantees a particular outcome - both are affected by how markets perform over the period you're invested. SIP simply spreads out your entry price over time, which some investors find more comfortable.
What is a step-up SIP?
A step-up SIP is a SIP where your monthly investment amount increases over time, usually in line with your income, instead of staying fixed for years.
Is a Systematic Transfer Plan (STP) the same as a SIP?
They're similar in mechanics - both move money in at regular intervals - but a SIP typically starts from your bank account, while an STP moves a lump sum that's already invested from one fund into another, gradually.